Sub-Saharan Africa's FMCG import market enters the final quarter of 2026 with a more resilient economic backdrop, but with renewed pressure from global food commodities, transport costs and geopolitical uncertainty.
The region's economy is projected to grow by 4.3% in 2026, up from an estimated 4.1% in 2025, according to the World Bank. Stronger domestic demand and improving macroeconomic resilience are supporting the recovery, although debt pressures, geopolitical tensions, climate shocks and trade uncertainty remain significant risks.
For FMCG companies, the implications are substantial.
The market is no longer defined simply by high inflation and consumer down-trading. In several major economies, inflation has moderated and consumer conditions are beginning to improve. At the same time, global food commodity prices have started rising again.
In September 2026, the FAO Food Price Index increased 1.5% month-on-month and 5.8% compared with September 2025. Cereal prices rose 5.1% during the month, vegetable oils increased 0.9%, and sugar prices climbed 6.1%.
This creates a more complex operating environment for importers and distributors.
Demand is recovering, but procurement costs remain vulnerable. Consumers are becoming more willing to spend, but affordability continues to influence purchasing decisions. And while global suppliers remain important, regional African supply chains are becoming increasingly competitive.
The result is an FMCG market in which price, product format, sourcing flexibility and distribution capability are becoming equally important competitive factors.
1. The Sub-Saharan African FMCG Market in Q4 2026
Sub-Saharan Africa remains one of the world's most important long-term consumer markets.
Population growth, urbanisation and rising demand for packaged products continue to support consumption of food, beverages, personal-care products, household goods and hygiene products.
But the region should not be treated as a single market.
Nigeria's consumer economy operates under very different conditions from Ghana's. Kenya differs from Ethiopia, while South Africa has a substantially more developed formal retail and manufacturing environment than many other markets.
This means FMCG import opportunities increasingly need to be assessed at the country, product and distribution-channel level.
The macroeconomic backdrop is nevertheless improving.
The World Bank's October 2026 Africa Economic Update projects regional growth of 4.3% in 2026, with growth forecasts upgraded for nearly three-quarters of countries in the region. Stronger domestic demand and greater macroeconomic resilience are driving the improvement.
However, the World Bank also highlights continuing risks from geopolitical tensions, climate shocks, trade-policy uncertainty, tighter financial conditions and fiscal pressures.
For FMCG businesses, this means the recovery should be viewed as an opportunity for selective expansion rather than an unrestricted return to volume growth.
2. Consumer Demand: From Inflation Shock to Selective Recovery
The consumer environment entering Q4 2026 differs from the one that dominated much of 2024 and 2025.
In several African economies, inflation has moderated substantially, while economic activity has strengthened.
This matters because FMCG demand is closely linked to household purchasing power.
When inflation accelerates faster than wages, consumers typically reduce discretionary purchases, switch brands or reduce pack sizes.
When inflation stabilises and incomes begin to recover, consumers can gradually return to branded products and higher-value categories.
The transition is already visible in several markets.
However, affordability remains central to FMCG strategy.
Consumers are unlikely to abandon value-oriented products simply because headline inflation is falling. Years of high food and living costs have changed purchasing behaviour, and many households remain highly price-sensitive.
This creates an increasingly important value ladder:
- entry-level products for price-sensitive consumers;
- mainstream branded products for the mass market;
- premium products for higher-income consumers;
- specialised and imported products serving urban and institutional niches.
Successful FMCG suppliers will increasingly need to operate across more than one of these segments.
3. Food Commodity Prices Are Becoming a Major Import Variable Again
The improvement in African inflation does not mean importers can assume that food input costs will remain stable.
FAO's September 2026 data show renewed pressure across several major agricultural commodities.
The FAO Food Price Index reached 136.0 points in September, up 1.5% from August and 5.8% from a year earlier. The increase was driven primarily by cereals, vegetable oils and sugar.
The cereal component is particularly important for African FMCG markets.
Global wheat prices increased 6.3% in September, with FAO pointing to logistical constraints in the Black Sea region and weather concerns in North America. Maize prices also increased as supply expectations tightened and export availability from Brazil and the Black Sea region was affected.
For African importers, these movements can eventually influence the cost of:
- flour;
- bread;
- pasta;
- biscuits;
- breakfast cereals;
- noodles;
- animal-feed-related food production;
- processed foods.
The impact is not immediate or identical across every market, but commodity price movements remain an important indicator of future import costs.
4. Wheat, Cereals and Processed Foods
Wheat remains one of the most strategically important food commodities for many African economies.
The importance of wheat imports extends well beyond household flour.
Imported wheat supports large downstream FMCG industries including bakeries, biscuit manufacturers, pasta producers, noodle manufacturers and other processed-food businesses.
This creates opportunities for both commodity suppliers and companies selling finished or semi-processed products.
The latest global supply situation is relatively strong. FAO estimates 2026 global cereal production at approximately 2.98 billion tonnes, which would still represent the second-largest harvest on record despite being 2.1% below the 2025 level.
The issue for African buyers is therefore less about whether global food supplies exist and more about where those supplies can be sourced competitively and reliably.
Black Sea logistics, freight costs, currency movements and port infrastructure can all influence the final landed cost.
This strengthens the case for sourcing diversification.
5. Edible Oils: A Category to Watch
Edible oils remain another major FMCG import category across Sub-Saharan Africa.
Palm oil, sunflower oil and soybean oil are used extensively in household cooking as well as food manufacturing.
The category is particularly exposed to international commodity markets.
FAO's September data show the Vegetable Oil Price Index rising 0.9% month-on-month and standing 18.3% above its September 2025 level. Palm oil prices increased for a fourth consecutive month, supported by strong global import demand and concerns about production conditions in Southeast Asia.
This creates potential margin pressure for importers and food manufacturers.
For FMCG distributors, consumer pack sizes will remain important. Smaller bottles and affordable unit prices can help products remain accessible even when commodity costs increase.
For manufacturers, meanwhile, sourcing flexibility becomes increasingly valuable.
6. Sugar and Sweetened Beverage Supply Chains
Sugar is another category experiencing renewed international price pressure.
FAO reports that international sugar prices increased 6.1% in September 2026, reaching their highest level since April 2025.
The increase reflects expectations of tighter global supplies in the 2026/27 season, including production concerns in Thailand and India and weather-related disruptions in Brazil and Europe.
This has implications beyond the sugar trade itself.
Sugar is an important input into:
- soft drinks;
- confectionery;
- biscuits;
- bakery products;
- processed foods;
- food-service products.
Consequently, changes in sugar prices can influence the cost structure of multiple FMCG categories simultaneously.
7. Beverages Remain a Major Growth Opportunity
Beverages remain one of the most commercially attractive FMCG categories in African urban markets.
Carbonated soft drinks, energy drinks, bottled beverages, juices and other ready-to-drink products benefit from urbanisation, changing lifestyles and the continent's young consumer population.
However, the structure of beverage imports is changing.
Large international beverage companies increasingly manufacture, bottle or blend products within African markets.
This reduces the requirement for finished-product imports while increasing opportunities for:
- beverage concentrates;
- flavourings;
- ingredients;
- packaging;
- production equipment;
- contract manufacturing;
- regional distribution.
Finished imported beverages can still succeed, particularly where they offer distinctive brands, flavours or price points.
But international suppliers increasingly need to consider whether the best route into an African market is exporting the finished product or establishing a local or regional production partnership.
8. Packaged Foods and Private Label
Packaged foods are positioned to benefit from both urbanisation and the expansion of modern retail.
Biscuits, noodles, canned foods, sauces, snacks, cereals and shelf-stable products are particularly suited to markets where consumers want convenience but remain price-conscious.
Private label is also becoming strategically important.
Retailers can use private-label products to offer consumers lower prices while maintaining control over margins and product positioning.
For manufacturers, this creates another route into African markets: instead of building a consumer brand from scratch, suppliers can work with established retailers, wholesalers and distributors to manufacture products for local or regional private-label programmes.
9. Personal Care and Household FMCG
The FMCG opportunity extends beyond food.
Personal-care products, cleaning products, detergents, hygiene products and household consumables benefit from the same structural forces driving food and beverage demand: population growth, urbanisation and increasing access to packaged consumer products.
The opportunity is particularly interesting for suppliers able to balance quality with affordability.
Small-format products can improve accessibility, while concentrated formulations and locally adapted packaging can help reduce transportation and distribution costs.
For exporters, regulatory compliance and product registration should be considered before entering individual markets, particularly for cosmetics, chemicals, hygiene products and products making health-related claims.
10. Africa's Regional Trade Opportunity Is Growing
One of the most important structural developments for FMCG businesses is the expansion of intra-African trade.
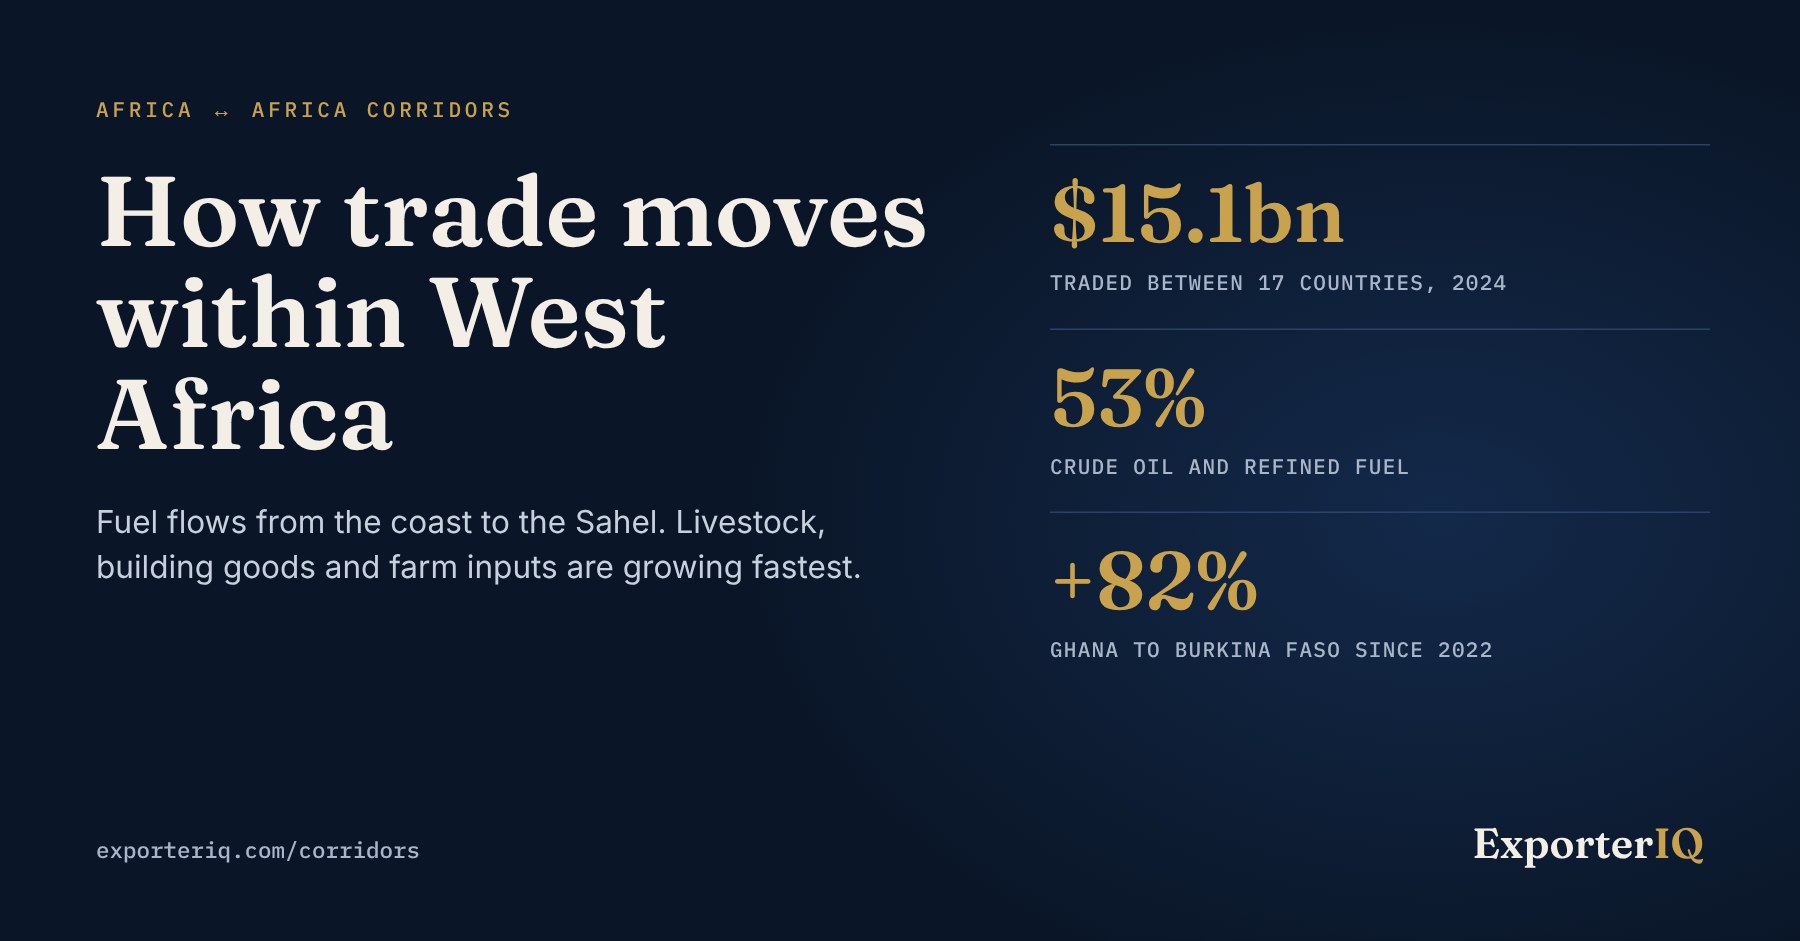
Afreximbank reports that intra-African trade increased 12.4% in 2024 to US$220.3 billion, rebounding strongly after a 5.9% contraction in 2023.
This is important because regional trade can create shorter and more flexible supply chains.
An FMCG manufacturer operating in one African market can potentially serve neighbouring countries without relying entirely on long-distance imports from Europe, Asia or the Americas.
This is particularly relevant for processed food, beverages, beauty products and other products where transportation costs represent a meaningful share of the final selling price.
South Africa remains a major driver of intra-African trade, while West and East African markets are developing increasingly important regional distribution networks.
11. AfCFTA: From Policy Framework to Commercial Opportunity
The African Continental Free Trade Area remains one of the most important long-term developments for African FMCG trade.
Its significance is not simply about reducing tariffs.
The larger opportunity is the creation of more integrated regional markets in which African manufacturers can achieve greater scale.
For FMCG companies, scale matters.
A manufacturer producing biscuits, beverages, personal-care products or packaged foods for one relatively small national market may struggle to achieve optimal production costs.
Access to neighbouring markets can change that equation.
However, businesses should not assume that AfCFTA automatically eliminates the practical challenges of cross-border trade.
Customs procedures, product standards, certification, transport infrastructure, foreign-exchange availability and non-tariff barriers continue to affect the cost and speed of regional trade.
The commercial opportunity therefore lies in identifying specific corridors where the regulatory and logistics environment is already workable.
12. The New Importance of Regional Distribution Hubs
The future African FMCG market is likely to be increasingly organised around regional hubs.
Rather than attempting to distribute products individually into dozens of countries, international suppliers can establish relationships with strong distributors serving regional markets.
Potential hubs include:
West Africa: Nigeria, Ghana and Côte d'Ivoire
East Africa: Kenya and Tanzania
Southern Africa: South Africa
Central Africa: Cameroon and other strategically positioned markets
These hubs can provide access to neighbouring markets while reducing the complexity of managing multiple independent supply chains.
For exporters, the distributor-selection process therefore becomes one of the most important components of market entry.
13. What Q4 2026 Means for FMCG Importers
Importers entering the final quarter of 2026 should focus on managing both demand opportunity and procurement risk.
Diversify sourcing
Do not rely unnecessarily on one country of origin or one shipping corridor.
Commodity markets and geopolitical conditions can change rapidly.
Monitor landed cost rather than factory price
A low supplier price does not necessarily mean a low-cost product.
Freight, insurance, duties, taxes, currency movements and inland logistics can materially change the final cost.
Consider regional suppliers
African manufacturers may offer shorter lead times and lower logistics costs for certain product categories.
Negotiate flexible purchasing arrangements
Smaller initial orders, staggered deliveries and flexible payment arrangements can reduce inventory and currency risk.
Track commodity prices
Wheat, vegetable oils, sugar and other commodities can influence FMCG margins months before the impact becomes visible at retail level.
Build multi-channel distribution
Modern retail is growing, but informal retailers remain essential to mass-market distribution in many countries.
14. What Q4 2026 Means for International Exporters
For international exporters, the African FMCG opportunity is increasingly about localisation.
The most competitive suppliers are likely to be those that understand:
Product-market fit
A product that sells well in Europe or Asia may require different packaging, flavours, pack sizes or price points in African markets.
Distribution
A strong local importer or distributor can be more valuable than a large advertising budget.
Pricing
African consumers are not necessarily looking for the cheapest product. They are looking for products that provide convincing value relative to their available income.
Local partnerships
Packaging, blending, manufacturing and distribution partnerships can make products more competitive than direct finished-goods imports.
Regional expansion
A successful entry into one country can provide a platform for expansion into neighbouring markets.
15. The Q4 2026 FMCG Opportunity by Category
The strongest opportunities are likely to remain concentrated in categories with recurring consumer demand and relatively resilient consumption.
These include:
Staple foods: wheat, flour, rice and other grains.
Edible oils: palm, sunflower and soybean oils.
Processed foods: noodles, biscuits, canned foods, sauces and packaged snacks.
Beverages: soft drinks, energy drinks, juices and other ready-to-drink products.
Dairy: powdered milk, UHT products and processed dairy.
Personal care: hygiene, skincare and everyday personal-care products.
Household products: detergents, cleaning products and other consumables.
FMCG inputs: ingredients, packaging materials, concentrates and other production inputs.
The strongest opportunity is not necessarily the category with the highest consumer growth.
It is the category where demand, supply availability, import economics and distribution capability intersect.
16. Q4 2026 Outlook
Sub-Saharan Africa's FMCG market enters the final quarter of 2026 with a stronger economic foundation than it had a year earlier.
Regional growth is improving, domestic demand is strengthening and inflation has moderated in several important economies. The World Bank expects growth of 4.3% across Sub-Saharan Africa in 2026.
But the operating environment remains volatile.
Global food prices have begun rising again, with FAO reporting significant increases in cereals, vegetable oils and sugar during September. Geopolitical tensions, weather conditions and transportation disruptions remain important risks for import-dependent economies.
At the same time, intra-African trade is expanding.
The 12.4% increase in intra-African trade recorded in 2024 demonstrates the potential of regional supply chains, even though major infrastructure and regulatory barriers remain.
This points to a market entering a new phase.
The next wave of FMCG growth in Africa is unlikely to come solely from importing more finished products.
It will increasingly come from better sourcing, regional manufacturing, local partnerships, smarter distribution and products designed around African market conditions.
Conclusion
Sub-Saharan Africa remains one of the world's most compelling long-term FMCG markets, but the opportunity in Q4 2026 is becoming more sophisticated.
Economic growth is strengthening, while inflation has eased in several major economies. Yet food commodity prices, logistics and geopolitical risks continue to influence the cost of importing and distributing consumer goods.
For importers, this means sourcing decisions need to go beyond supplier price.
For exporters, success increasingly depends on product adaptation, local partnerships and distribution.
For African manufacturers, the expansion of intra-African trade creates an opportunity to move beyond individual national markets and build regional supply chains.
And for distributors, the ability to connect international and regional suppliers with fragmented consumer markets remains a significant competitive advantage.
The central opportunity is therefore not simply selling more FMCG products into Africa.
It is building supply chains that are affordable, reliable, locally relevant and capable of serving multiple African markets.
That is likely to define the next stage of FMCG trade across Sub-Saharan Africa.
Sources: Key sources
- World Bank: Africa Economic Update, October 2026
This is the most important source for the overall macroeconomic outlook. It projects Sub-Saharan African growth of 4.3% in 2026, up from 4.1% in 2025, while noting that median inflation is expected to rise to 5.5% because of higher food, fuel and fertiliser prices.
World Bank: Africa Economic Update
- FAO: Food Price Index, September 2026
Particularly useful for the article's discussion of food commodities, cereals, vegetable oils and sugar. The September 2026 index increased 1.5% month-on-month and 5.8% year-on-year, with transport disruptions and weather concerns contributing to higher prices.
FAO Food Price Index - FAO: Food Outlook
This is the best ongoing source for wheat, rice, cereals, vegetable oils, sugar and other internationally traded food commodities. FAO's 2026 Food Outlook releases are scheduled for June 18 and November 12, so the November edition will be particularly useful for a later Q4 update.
FAO Food Outlook - IMF: Ghana, 2026 Article IV Consultation
Useful for the Ghana section. The IMF reports that Ghana's GDP grew 6% in 2025 and 6.4% year-on-year in Q1 2026, while headline inflation fell to 5.3% in June 2026.
IMF: Ghana 2026 Article IV Consultation - IMF: Inflation in Nigeria: A Descriptive Analysis of Recent Developments
This supports the Nigeria discussion around inflation, food prices, exchange-rate depreciation and the effect of recent reforms. The IMF notes that inflation persistence has declined and that the economy has become more responsive to monetary policy.
IMF: Inflation in Nigeria - Afreximbank: African Trade Report 2025
This is particularly valuable for the article's AfCFTA/intra-African trade section. Intra-African trade increased 12.4% in 2024 to approximately US$220.3 billion, after contracting in 2023. Afreximbank
Afreximbank: African Trade Report 2025 - UNCTAD: AfCFTA Non-Tariff Barriers
Good source for the point that customs procedures, import restrictions, sanitary/technical requirements and other non-tariff barriers continue to affect intra-African trade. UNCTAD
UNCTAD : AfCFTA Non-Tariff Barriers Mechanism
Written by Andre Biyog, ExporterIQ.